Executive Overview
The landscape of home entertainment has completed a profound, ironic full circle. Over a decade ago, subscription video-on-demand (SVOD) platforms heralded a utopian era for consumers. For a modest monthly fee—often under £6 in the United Kingdom—viewers were promised an expansive, uninterrupted library of feature films and television series, entirely free of commercial breaks, long-term contracts, and the clunky hardware of traditional satellite or cable dishes. It was marketed as the ultimate consumer empowerment: television on your own terms, when you wanted it, completely ad-free.
Fast forward to the present day, and that utopian vision has largely evaporated, replaced by a complex corporate ecosystem that bears an uncanny resemblance to the very traditional broadcasting models it once sought to destroy. Following successive rounds of aggressive price increases, standard ad-free subscriptions have climbed steeply—with entry-level plans starting at £13.99 a month and premium tiers reaching upward of £20.99.
Worse still, the sacred boundary separating paid subscriptions from commercial advertising has been systematically dismantled. Platforms like Amazon Prime Video integrated ads by default, charging an additional monthly premium to remove them. Disney+ updated its subscriber agreements to state that all tiers "may include" promotional content, sponsorships, and commercial breaks before or after playback. Netflix, meanwhile, has steadily grown its cheaper ad-supported tier while simultaneously hiking its price by a third, jumping from £5.99 to £7.99.
We set out to escape the expense, the rigidity, and the commercial interruptions of traditional cable television. Instead, through a combination of fragmented app ecosystems, bundled subscriptions, and creeping ad integration, we have simply reinvented cable TV over the internet—just at a significantly higher total cost.
Detailed Chronology: The Evolution and Commodification of Streaming
To understand how modern streaming arrived at this financial crossroad, it is necessary to examine the historical trajectory of the industry over the past decade and a half.
The Utopian Era (2012–2016)
In the early 2010s, streaming was defined by aggressive market penetration and customer acquisition. Services like Netflix operated at staggering financial losses, subsidized by venture capital and enthusiastic Wall Street investors who prioritized subscriber growth numbers above all else. For consumers, this era was defined by incredible value. Platforms were flush with licensed content from major Hollywood studios, and the user experience was clean, fast, and remarkably cheap. The cultural zeitgeist embraced streaming as a revolutionary equalizer that democratized access to premium media.
The Content Wars and Market Fragmentation (2017–2020)
Realizing they were handing their most valuable intellectual properties to a third-party distributor, traditional media conglomerates decided to launch their own direct-to-consumer platforms. Disney, Warner Bros., NBCUniversal, and Paramount pulled their catalogs from Netflix to build proprietary silos. Suddenly, the consumer’s singular monthly subscription fee fractured into a half-dozen distinct payments. If you wanted Disney content, you needed Disney+. If you wanted HBO prestige dramas, you needed Max. The cost-saving promise of "cutting the cord" began to erode as the cumulative cost of maintaining multiple subscriptions started matching or exceeding legacy cable bills.
The Growth Wall and the Pivot to Profitability (2021–2022)
The inflection point arrived in early 2022, when Netflix stunned Wall Street by reporting its first major subscriber downturn in a decade. Market saturation had hit: virtually everyone who wanted a streaming service already had one. Consequently, subscriber growth flattened. Wall Street’s tolerance for multi-billion-dollar corporate losses vanished overnight, and executive boards were forced to pivot from an aggressive "growth-at-all-costs" model to an aggressive "profit-maximization" strategy. Because subscriber counts could no longer scale upward exponentially, platforms had to extract more capital from each existing user.
The Commercialization Wave (2022–Present)
Faced with the imperative to boost average revenue per user (ARPU), the industry systematically dismantled the ad-free baseline promise.
- November 2022: Netflix launched its lower-cost, ad-supported tier in the UK for £4.99, framing it as a way to give consumers "more choice." Shortly after, it phased out its cheapest ad-free tier for new subscribers, forcing users into higher-priced brackets to avoid commercials.
- February 2024: Amazon Prime Video shifted its entire subscriber base onto an ad-supported model by default, requiring an additional monthly surcharge of £2.99 to restore an ad-free experience.
- Late 2024 and Beyond: Disney+ followed suit by introducing its own ad tiers and updating subscriber agreements to weave promotional content and sponsorships deeply into the user journey, even on upper-tier plans.
Supporting Context & Metrics: The Math Behind the Streaming Squeeze
The financial restructuring of the streaming industry is driven by basic corporate arithmetic. As growth models stalled, companies found themselves squeezed between rising production budgets for prestige content and static user bases.
[ Traditional Cable TV ]
       │
       ▼  (Disrupted by)
[ Early Streaming Utopia ] (Low cost, ad-free, rapid subscriber growth)
       │
       ▼  (Triggered by Market Saturation & 2022 Subscriber Downturn)
[ The Pivot to Profitability ]
       ├── Subscription Price Hikes (£13.99 - £20.99 / month)
       └── Reintroduction of Ads (Tiers, bundled packages, forced upgrades)
       │
       ▼  (Result)
[ "Neo-Cable" Era ] (Fragmented apps, higher total costs, commercial interruptions)
To maintain profit margins while producing hundreds of millions of dollars’ worth of original programming annually, streaming giants leverage a two-pronged revenue engine:
- Vertical Price Discrimination: Raising the baseline cost of ad-free viewing while positioning the ad-supported tier as the affordable alternative.
- Double-Dip Monetization: Collecting subscription fees from the user while simultaneously selling high-yield, targeted digital ad spaces to corporate brands.
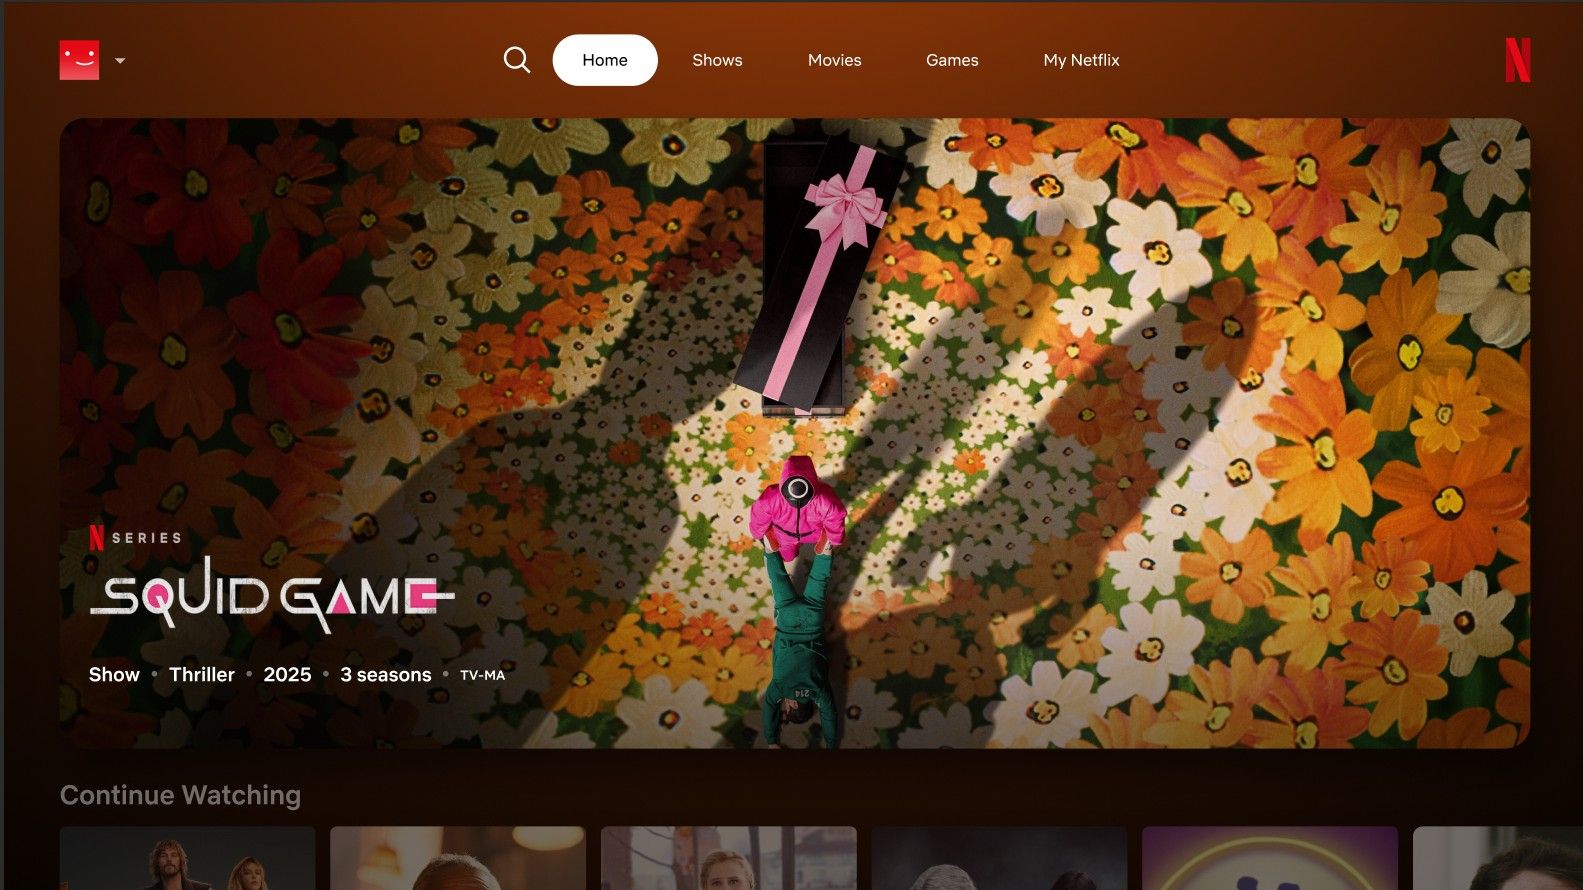
According to media analysts, the average digital consumer now subscribes to between three and five distinct video-on-demand services simultaneously. When combined with broadband internet costs required to stream high-definition and 4K content, the monthly household expenditure on home entertainment frequently surpasses the peak prices of legacy cable and satellite bundles. Furthermore, modern streaming aggregators—such as Sky, Virgin Media, and telecommunications providers in North America—have repackaged these standalone apps into digital "bundles" that mirror traditional channel packages down to the user interface.
Official Statements and Industry Rationalizations
Industry executives have defended these structural shifts by framing them around consumer flexibility and economic sustainability.
When introducing ad-supported tiers, corporate representatives consistently emphasize that advertising enables lower entry barriers for cost-conscious households. A spokesperson for Netflix previously noted that ad-supported models allow the platform to offer "a lower price for consumers and a robust choice of plans," ensuring that entertainment remains accessible during periods of broader economic inflation.
Similarly, corporate communications from Disney and Amazon regarding updated contractual terms have emphasized that promotional content and sponsored integrations are designed to be minimally intrusive. Disney’s recent subscriber agreement updates clarify that sponsorships and promotional messages are integrated to support ongoing content investment, maintaining that standard ad-free tiers will not suddenly mirror traditional broadcast television’s aggressive commercial breaks—at least, not yet.
Independent media analysts, however, view these statements as calculated incremental steps. Consumer advocacy groups have criticized the shifting legal definitions within terms-of-service agreements, arguing that companies are slowly conditioning audiences to accept a creeping baseline of commercial interruptions where none previously existed.
Future Outlook: The Consumer’s Ultimate Weapon
As the streaming market settles into this "neo-cable" era characterized by higher prices, fragmented app ecosystems, and pervasive advertising, the psychological contract between viewer and platform has fundamentally changed. We are no longer experiencing a radical technological revolution; we are simply participating in a modernized, internet-delivered broadcasting industry.
However, modern consumers retain one critical advantage that legacy cable and satellite subscribers never possessed: frictionless cancellation.
In the era of traditional pay-TV, canceling a subscription required cumbersome phone calls, cancellation fees, equipment returns, and lengthy contract lock-ins. Today, canceling a digital streaming service takes less than thirty seconds with a few clicks of a remote control. Furthermore, the burgeoning marketplace of Free Ad-Supported Streaming Television (FAST) channels provides an ample safety net for viewers unwilling to pay soaring subscription fees.
As households evaluate their monthly expenses against the backdrop of an increasingly crowded and commercialized media landscape, the ultimate power rests with the viewer. The next time you sit down on the couch, scroll endlessly through an inflated home screen, and realize that your favorite show is now split across multiple paid tiers or interrupted by sponsored segments, remember that you are not locked into a two-year contract. The remote control—and the cancel button—remains firmly in your hands.